
Featured By Matthew Otabe
From over 100 fragmented levies to nine harmonised tax heads, 100 million-plus Tax IDs and 27 per cent revenue growth, early indicators point to a shift towards a simpler, fairer and more transparent tax system.
Nigeria’s tax reform agenda is beginning to move beyond legislation and policy discussions into practical changes in revenue administration, taxpayer identification, state-level revenue performance and the relationship between government and taxpayers.
For years, Nigeria’s tax environment has been characterised by fragmented levies, overlapping tax obligations, inconsistent administration and compliance processes that impose significant costs on individuals and businesses. For many taxpayers, navigating the system has often meant dealing with multiple authorities, unclear responsibilities and a lack of uniformity across jurisdictions.
The new tax administration framework seeks to change that experience.
Its central ambition is to build a tax system that raises revenue without unnecessarily constraining investment, discouraging enterprise or placing disproportionate burdens on vulnerable households and small businesses.
The philosophy behind the reform is captured in a simple principle: tax prosperity, not poverty; tax the fruit, not the seed; tax the return, not investment.
This represents a shift towards a revenue system that recognises the importance of economic growth, productive investment and the capacity of taxpayers to meet their obligations.
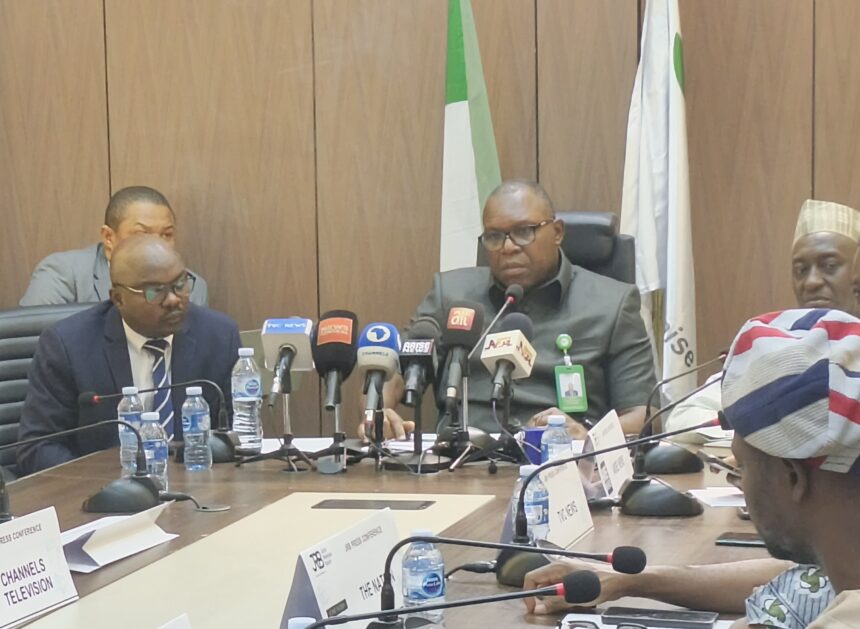
As implementation progresses, early indicators presented by the Joint Revenue Board (JRB) suggest that the reform is beginning to influence how taxes are identified, administered, harmonised and collected across the country.
A New Philosophy of Taxation
At the heart of the reform is the recognition that an effective tax system must do more than generate revenue. It must also inspire confidence, promote fairness and establish a clear relationship between what government collects and how public resources are used.
Four principles guide the implementation process: fairness, equity, accountability and transparency.
Fairness requires taxpayers to be treated impartially, without preferential or discriminatory policies. Equity demands that tax obligations reflect differences in taxpayers’ ability to pay, including the circumstances of individuals and businesses operating in the formal and informal sectors.
Accountability requires the judicious use of tax revenue for economic development, while transparency places responsibility for tax assessment, collection and reporting on clearly identifiable authorities.
Together, these principles are intended to strengthen voluntary compliance by making the tax system more understandable, predictable and credible.
The reform also seeks to modernise Nigeria’s tax framework by addressing inconsistencies and overlapping taxes, reducing the cost of compliance through technology and strengthening revenue mobilisation in ways that support economic growth.
The underlying objective is to build a system in which paying taxes becomes less complicated, administration becomes more efficient and government revenue grows alongside economic activity.
Personal Income Tax: Relief for Earners
One of the most significant changes highlighted in the reform framework concerns the personal income tax regime introduced from January 2026.
Under the previous structure, the first ₦300,000 of chargeable income was taxed at seven per cent, with progressively higher rates applying to subsequent income bands. The highest rate shown in the previous schedule was 24 per cent.
Under the new framework, the first ₦800,000 of chargeable income attracts a zero per cent rate. Subsequent bands are taxed at 15, 18, 21 and 23 per cent, while income above ₦50 million attracts a rate of 25 per cent.
The revised structure is designed to provide relief at the lower end of the income scale while applying progressive rates to higher earnings.
The JRB’s presentation illustrates the potential impact using an individual with annual chargeable income of ₦20 million.
Under the previous schedule, the annual tax payable was calculated at ₦4.592 million, leaving monthly take-home income of approximately ₦1.284 million.
Under the new schedule, the presentation puts annual tax payable at ₦3.63 million and monthly take-home income at approximately ₦1.364 million.
This translates to an estimated increase in monthly disposable income of ₦80,167, or about ₦962,004 annually.
The illustration demonstrates how changes to tax bands can affect household finances, although the actual tax payable by an individual will depend on the applicable rules and eligible deductions.
The broader policy direction is to ensure that taxation does not unnecessarily erode the earnings of workers or discourage productive economic activity.
One Tax Identity, More Efficient Administration
A major challenge in revenue administration is the ability to identify taxpayers accurately and consistently across different government systems.
The JRB reports that more than 100 million Tax Identification Numbers have been assigned under the reform framework, representing a significant step towards a more coordinated taxpayer identification system.
Individuals can retrieve their Tax IDs using their National Identification Number, while registered businesses can use their Corporate Affairs Commission registration numbers.
The identifiers can be retrieved through the designated JRB and Nigeria Revenue Service platforms.
A more unified identification system can help revenue authorities improve taxpayer records, reduce duplication and strengthen the administration of tax obligations.
It also provides a foundation for more efficient digital services, allowing taxpayers to interact with the system without unnecessarily repeating registration processes across different institutions.
The reform’s emphasis on technology is particularly important in a country where businesses and individuals increasingly expect public services to be accessible through digital platforms.
For revenue authorities, digitisation offers opportunities to improve record management, reduce manual processes and make compliance easier to monitor.
However, the long-term value of the system will depend on its effective implementation, the accuracy of taxpayer records and the ability of relevant authorities to coordinate their operations.
Revenue Growth Across States
Beyond changes to tax administration, early figures suggest that states are beginning to record improvements in internally generated revenue.
According to the JRB, data submitted by 23 states show a 27 per cent year-on-year increase in internally generated revenue for the first half of 2026 compared with the corresponding period of 2025.
The figure provides an early indication of improved revenue performance among the reporting states.
However, the result should be interpreted within its stated scope: it covers 23 states and does not, by itself, establish the performance of every state or prove that the entire increase resulted solely from the new tax framework.
Nevertheless, the reported growth offers an important basis for assessing how states are responding to the evolving revenue administration environment.
For subnational governments, stronger internally generated revenue can improve fiscal capacity and reduce dependence on external allocations, provided that increased collections are accompanied by responsible public spending.
The challenge is to sustain revenue growth without imposing excessive burdens on households, traders, small businesses and productive enterprises.
That balance will be central to determining whether improved revenue mobilisation translates into broader economic benefits.
Ending the Burden of Fragmented Levies
Perhaps one of the most visible objectives of the reform is the harmonisation of taxes and levies.
Nigeria’s fragmented system has often exposed businesses, traders and transport operators to multiple charges imposed by different authorities. Such practices can increase operating costs, create uncertainty and complicate the movement of goods across state boundaries.
The new framework seeks to replace more than 100 fragmented taxes and levies at the subnational level with nine harmonised tax heads.
These include income tax, stamp duties, property tax, road tax, haulage levy, economic development levy, harmonised levy, user charge and daily ticket.
The intention is to establish a more coherent structure for revenue collection, reduce duplication and clarify the categories of charges that may lawfully be imposed.
The JRB reports that 21 states have passed the Model Harmonised Taxes and Levies Law.
The states listed in its October 2026 presentation are Kebbi, Kaduna, Zamfara, Ekiti, Enugu, Abia, Anambra, Gombe, Adamawa, Yobe, Borno, Niger, Plateau, Benue, Kogi, Kwara, Nasarawa, Akwa Ibom, Bayelsa, Delta and Ondo.
The adoption of the model law across these states represents progress towards a more uniform subnational tax administration system.
For businesses operating across multiple states, harmonisation could reduce the cost of understanding and complying with different local requirements.
For farmers and distributors, it could also help reduce the additional costs associated with moving agricultural produce and other goods from one location to another.
The wider economic significance lies in the possibility of making commerce less cumbersome while ensuring that governments retain legitimate and clearly defined revenue sources.
No More Stickers, Emblems and Roadside Cash Collection
The reform also targets practices that have long generated complaints among motorists, traders and transport operators.
At its 158th meeting, the JRB announced a ban on the sale of stickers and emblems nationwide under the harmonisation initiative.
The measure is intended to prevent motorists and businesses from being subjected to demands for irrelevant documents or additional charges while transporting goods from one part of the country to another.
By removing such requirements, the framework seeks to reduce unnecessary expenses and improve the movement of goods across state boundaries.
Another important objective is the elimination of roadblocks and cash-based tax collection.
The JRB’s presentation states that the model harmonised taxes and levies framework, together with the Presumptive Tax Regulations 2026, provides a basis for addressing these practices.
The Board says its position is one of zero tolerance for roadblocks and cash collection, with collaboration involving the Nigeria Police Force ongoing and enforcement expected to commence soon.
The success of this initiative will depend heavily on enforcement. A ban on unlawful or unauthorised collections will have limited impact if motorists and traders continue to encounter roadside demands for cash or face intimidation by individuals claiming to represent revenue authorities.
Effective implementation will therefore require coordination among tax authorities, security agencies and the relevant state and local government institutions.
It will also require accessible channels through which taxpayers can report violations and obtain timely responses to complaints.
Bringing the Informal Sector Into the System
The informal sector presents a particularly important challenge for tax administration.
Millions of Nigerians earn their livelihoods through small-scale trading, food vending, transportation, personal services and other activities that may not be supported by sophisticated accounting systems.
An effective tax framework must recognise the differences between these businesses and larger enterprises.
The JRB says the Presumptive Tax Regulations 2026 are intended to establish a simpler and more uniform framework for taxing the informal sector.
Under the provisions highlighted in its presentation, nano traders with annual turnover of ₦12 million or less are exempt from tax.
Other listed categories exempted under the framework include roadside food vendors, mobile barbers, manual tailors, local cobblers, newspaper vendors, wheelbarrow pushers, car-wash boys and phone-charging station operators.
The framework also provides for tax exemption certificates to be issued to nano businesses free of charge.
These measures reflect an attempt to avoid imposing disproportionate compliance costs on people whose businesses operate on a small scale.
For many microbusinesses, the expense and complexity of formal tax compliance can be as significant a concern as the amount of tax payable.
A simpler framework can help address that challenge while providing clearer guidance on who is liable to pay tax and who qualifies for exemption.
The effectiveness of the policy will depend on whether the exemptions are properly communicated and consistently respected by the officials responsible for enforcement.
It will also depend on ensuring that small businesses are not subjected to unofficial charges under the guise of tax collection.
Technology and Capacity Building
Tax reform requires more than new laws and regulations. It also demands changes in the way revenue authorities operate.
The JRB reports that states are increasingly embracing technology for revenue administration, with some already benefiting from technology interventions supported by the Board.
Digital systems can help improve the efficiency of registration, assessment, payment and reporting, while reducing dependence on manual processes.
The Board has also organised training programmes for revenue officers and other stakeholders to familiarise them with the new tax laws, processes and practices.
The training covers emerging areas such as the taxation of the digital economy, which presents new administrative challenges as commercial activities increasingly take place through online platforms and digital services.
Such capacity-building initiatives are important because uniform tax laws cannot produce uniform outcomes if the officials implementing them operate with different levels of understanding.
A coordinated approach to training, interpretation and enforcement can help reduce inconsistencies and improve taxpayers’ experience across jurisdictions.
The JRB has also issued guidelines and advisories to support the uniform application of the new tax laws.
These include Personal Income Tax Administration Guidelines, guidelines for implementing subnational harmonised tax rates and guidelines on the taxation of winnings.
The aim is to ensure that the reform is implemented through common standards rather than fragmented interpretations by individual authorities.
The Tax Ombud: A New Avenue for Redress
A credible tax system must provide taxpayers with a means of challenging decisions they consider unfair.
Recognising this need, the JRB reports that an independent Tax Ombud Office is now operational.
The office is intended to serve as an impartial mechanism for reviewing and resolving complaints relating to taxes, levies, regulatory fees, customs duties and excise matters.
Its functions include reviewing complaints against tax officials and authorities, facilitating mediation or conciliation, and investigating complaints concerning the actions or decisions of tax agencies and their officials.
The establishment of the office introduces an additional avenue through which taxpayers can seek redress without relying exclusively on the authorities whose actions they are challenging.
For businesses and individuals, an accessible and independent complaints mechanism can help improve confidence in the tax administration system.
For revenue authorities, it can provide an opportunity to identify recurring administrative problems, address misconduct and improve service delivery.
Its credibility will ultimately depend on its independence, accessibility, fairness and ability to resolve complaints effectively.
An office designed to protect taxpayers must be able to provide meaningful redress when complaints are justified, while ensuring that disputes are handled impartially.
From Revenue Collection to Economic Development
The ultimate test of tax reform is not simply whether government collects more money. It is whether the system creates a more sustainable relationship between revenue mobilisation and economic development.
The JRB’s framework emphasises that tax revenue should be used judiciously to support development.
This principle is particularly important in an economy where households and businesses face competing demands on their limited resources.
Taxpayers are more likely to comply voluntarily when they understand their obligations, believe that the rules are applied fairly and have confidence that public resources are being managed responsibly.
Conversely, complicated rules, overlapping charges, arbitrary enforcement and limited access to redress can undermine confidence and encourage resistance to compliance.
The reform’s emphasis on simpler tax structures, digital administration, harmonised levies and taxpayer protection is therefore an attempt to address both the administrative and public-confidence dimensions of taxation.
By reducing unnecessary burdens and improving the clarity of tax obligations, the government hopes to create an environment in which revenue mobilisation can grow without unnecessarily discouraging investment and enterprise.
The Road Ahead
The early indicators presented by the JRB show progress across several areas: more than 100 million Tax IDs assigned, a reported 27 per cent increase in internally generated revenue across 23 reporting states, adoption of the Model Harmonised Taxes and Levies Law by 21 states, and the introduction of measures aimed at reducing fragmented levies and simplifying taxation for small businesses.
These developments provide a basis for assessing the reform’s initial direction.
However, the figures represent early implementation indicators rather than conclusive evidence of the reform’s long-term impact.
The durability of the gains will depend on consistent enforcement, cooperation among federal and subnational authorities, reliable digital systems, effective taxpayer education and the ability to prevent unauthorised collections.
States that have yet to adopt the harmonised framework will also need to determine how to align their revenue administration practices with the reform’s objectives.
For taxpayers, the key question is whether the changes will translate into a more predictable and less burdensome experience when meeting their obligations.
For government, the challenge is to sustain revenue growth while ensuring that taxation remains fair, transparent and supportive of economic activity.
Ultimately, the success of the new framework will be measured not only by the amount of revenue collected, but also by the confidence it inspires, the compliance costs it reduces and the economic opportunities it helps preserve.
Nigeria’s tax reform is therefore a work in progress. Its early outcomes suggest a movement towards a more coordinated and technology-driven system, but sustained implementation will determine whether the promise of a simpler, fairer and more accountable tax administration becomes a lasting reality.