

By Ummie Kabir
The Central Bank of Nigeria’s (CBN) decision to slash its benchmark interest rate by 350 basis points has triggered debate over whether the move will stimulate production and investment or expose the economy to renewed inflationary and exchange-rate pressures.
The reduction, which lowered the Monetary Policy Rate (MPR) from 26.5 per cent to 23 per cent, represents one of the most significant monetary policy adjustments in nearly two decades.
While some reports have described it as the largest rate cut on record, others have pointed to a 400-basis-point reduction during the Charles Soludo era in December 2006.
Regardless of the historical comparison, the decision marks a significant shift for a central bank that has maintained a tight monetary policy stance over the past two years to contain inflation and stabilise the naira.
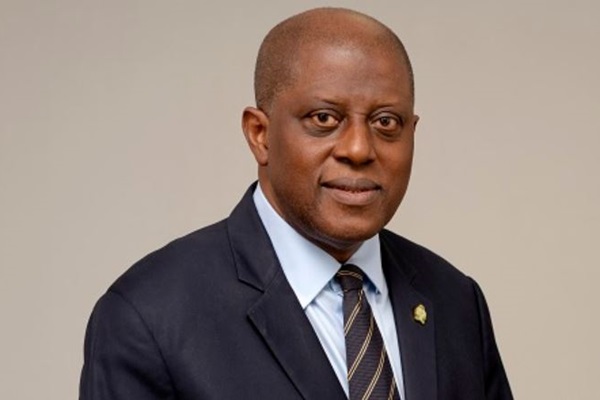
Announcing the outcome of the 307th Monetary Policy Committee (MPC) meeting, CBN Governor Olayemi Cardoso described the decision as a “reset and recalibration” rather than a conventional shift towards monetary easing.
According to the apex bank, the adjustment was intended to address a disconnect between the policy rate and effective market interest rates, while improving the effectiveness of monetary policy ahead of the planned transition to an inflation-targeting framework.
The distinction is important. However, the ultimate test of the decision will be whether it translates into lower borrowing costs, increased private-sector investment and sustainable economic growth without undermining price and exchange-rate stability.
The Case for the Rate Cut
For Nigerian businesses, particularly manufacturers, farmers and traders, the reduction offers a potential reprieve from prohibitively expensive borrowing.
With the MPR previously standing at 26.5 per cent, commercial lending rates of 30 per cent or higher made it difficult for many businesses to secure loans capable of supporting profitable expansion.
At such costs, manufacturers face significant challenges financing new equipment, expanding production lines and maintaining working capital. Small businesses also struggle to borrow for inventory, logistics and other essential operations.
Recent data cited in the debate over monetary policy indicated that private-sector credit had declined by approximately ₦10.3 trillion over seven months, highlighting concerns about access to financing for productive activities.
A lower benchmark rate could encourage banks to reduce lending rates, improve credit availability and support businesses seeking to expand their operations.
If effectively transmitted through the banking system, the decision could help manufacturers increase production, farmers invest in modern equipment and entrepreneurs create additional employment opportunities.
The inflation outlook also provides some justification for the move.
Nigeria’s headline inflation rate eased for the third consecutive month to 14.63 per cent in September 2026, strengthening the argument that some monetary policy adjustment may be warranted.
With inflation declining, maintaining the MPR at 26.5 per cent would have left the nominal policy rate substantially above the prevailing inflation rate, imposing considerable financing costs on businesses.
The CBN has also cited improving economic growth, relative exchange-rate stability and stronger external reserves as factors supporting its decision.
Another potential benefit is the effect on government borrowing costs.
A reduction in the benchmark rate could eventually contribute to lower yields on government securities, depending on market expectations and liquidity conditions. This could reduce the cost of domestic borrowing and create additional fiscal space for infrastructure and other capital projects.
However, such benefits are neither immediate nor guaranteed. They depend on how financial markets respond and whether the adjustment translates into lower borrowing costs across the economy.
The Risks Behind Cardoso’s Decision
Despite the potential benefits, the rate cut carries significant risks, particularly because the decline in inflation may not yet be sufficiently entrenched.
Some analysts have cautioned that rising global oil prices, elevated energy and transportation costs, and possible increases in government spending ahead of the 2027 general elections could reignite inflationary pressures.
Nigeria’s economic experience has repeatedly demonstrated how fiscal expansion, supply-side constraints and excessive liquidity can combine to undermine price stability.
If lower interest rates coincide with increased government spending and stronger demand without a corresponding expansion in domestic production, inflation could accelerate again.
The CBN would then face the difficult task of tightening monetary policy once more, potentially reversing some of the benefits expected from the current adjustment.
The Naira Under Pressure
The foreign-exchange market presents another major concern.
High domestic interest rates have helped attract foreign portfolio investors seeking relatively attractive returns on Nigerian financial assets.
Reducing the MPR could narrow that advantage, potentially weakening the incentive for some investors to maintain or increase their exposure to naira-denominated instruments.
If foreign portfolio inflows slow or investors withdraw funds, pressure could build on the exchange rate.
A weaker naira would increase the cost of imported machinery, industrial components, raw materials and other essential production inputs.
This could undermine the very manufacturers the rate cut is intended to support, particularly businesses that depend heavily on imported materials.
Consequently, exchange-rate stability, which the CBN has identified as one of the conditions supporting the adjustment, could also become one of its most significant vulnerabilities.
The outcome will depend on several factors beyond interest rates, including foreign-exchange supply, external reserves, export earnings, investor confidence and the broader global economic environment.
Will Lower Rates Translate Into Cheaper Loans?
Perhaps the most important question is whether the reduction will meaningfully lower borrowing costs for businesses.
The CBN’s high cash reserve requirement, which has stood at 45 per cent for deposit money banks, remains a significant constraint on the amount of deposits available for lending.
With a substantial proportion of deposits required to be held as reserves, banks may have limited room to expand credit, regardless of the reduction in the policy rate.
Lending decisions are also influenced by credit risks, collateral requirements, the financial health of borrowers and the attractiveness of alternative investment opportunities.
Government securities may continue to appeal to banks because they are generally considered less risky than lending to small businesses with limited credit histories or uncertain cash flows.
Consequently, a lower MPR does not automatically guarantee cheaper loans for manufacturers, farmers and other private-sector operators.
Without complementary measures addressing credit guarantees, collateral requirements and the structural constraints affecting bank lending, the benefits of the rate cut may not reach the businesses that need them most.
The reduction therefore creates an opportunity for cheaper credit, but the extent to which that opportunity becomes reality will depend on the response of financial institutions and the wider policy environment.
Winners and Losers
The rate cut is also likely to produce different outcomes for various segments of the economy.
Businesses that rely on borrowing to finance expansion could benefit if commercial lending rates decline.
Lower financing costs could enable manufacturers to acquire equipment, increase production and employ additional workers. Small businesses could also find it easier to finance inventory, improve operations and respond to market opportunities.
The government could benefit if the adjustment eventually lowers the cost of domestic borrowing, although the effect would depend on investor expectations and the broader yield environment.
However, savers and investors who depend on fixed-income instruments could face lower returns as yields adjust to the new policy rate.
Pensioners, small depositors and other individuals relying on interest income may also experience reduced earnings.
Although inflation has moderated, it continues to affect household purchasing power. If deposit rates decline faster than inflation, savers could experience weaker real returns on their money.
The challenge for the CBN is therefore to balance the need to stimulate productive economic activity against the risks of inflation, exchange-rate instability and reduced returns for savers.
What to Watch in the Coming Months
The next few months will provide critical evidence of whether the rate cut was appropriately timed.
First, commercial lending rates must respond. The key question is whether banks reduce their lending rates sufficiently to make borrowing more affordable for businesses. A lower MPR that fails to translate into cheaper credit would have limited benefits for the productive economy.
Second, inflation must continue to moderate. Future inflation reports, particularly developments in food, energy and transportation prices, will help determine whether the CBN acted at the right time.
A renewed acceleration in inflation could weaken the case for further monetary easing.
Third, the naira must remain reasonably stable. Movements in the exchange rate and foreign portfolio investment flows will be important indicators of investor confidence following the decision.
Significant capital outflows or sustained pressure on the naira could complicate the CBN’s efforts to maintain macroeconomic stability.
Fourth, the CBN’s other policy measures will matter. Any adjustment to cash reserve requirements or complementary credit-support measures could influence how effectively the rate reduction reaches businesses.
Finally, the government must ensure that fiscal policy supports rather than undermines monetary policy. Excessive spending without corresponding improvements in productivity could increase inflationary pressures and weaken the benefits of lower interest rates.
The Verdict: A Defensible but High-Stakes Gamble
Cardoso’s 350-basis-point reduction represents a significant monetary policy decision that could provide relief to Nigeria’s productive sector, but its success will depend on the conditions that follow.
The CBN has made a defensible case that declining inflation and the need to improve monetary policy transmission justify recalibrating the benchmark rate.
If inflation continues to fall, the naira remains stable and banks extend more affordable credit to businesses, the decision could be remembered as a timely adjustment that gave Nigerian producers room to breathe.
However, if the reduction fuels inflation, weakens investor confidence or fails to translate into lower borrowing costs, the expected economic benefits could prove disappointing.
More importantly, cheaper money alone cannot resolve the structural challenges confronting Nigerian businesses.
Unreliable electricity, insecurity, inadequate transportation infrastructure, high logistics costs and difficulties accessing foreign exchange continue to constrain production and competitiveness.
A manufacturer may obtain a loan at a lower interest rate but still struggle to operate a factory without reliable power. A farmer may secure financing but remain unable to transport produce to markets at competitive costs.
The government must therefore complement monetary policy adjustments with sustained investment in infrastructure, improved security, efficient logistics and policies that encourage domestic production.
Ultimately, Cardoso’s rate cut should be judged not by the size of the reduction or the immediate reaction of financial markets, but by its impact on production, employment, investment and the cost of living.
The real test is whether the policy can move Nigeria from expensive credit and constrained production towards sustainable business growth without sacrificing the gains made in stabilising inflation and the naira.